Good Monday morning from your Hometown Lender. Here is your Monday market analysis!
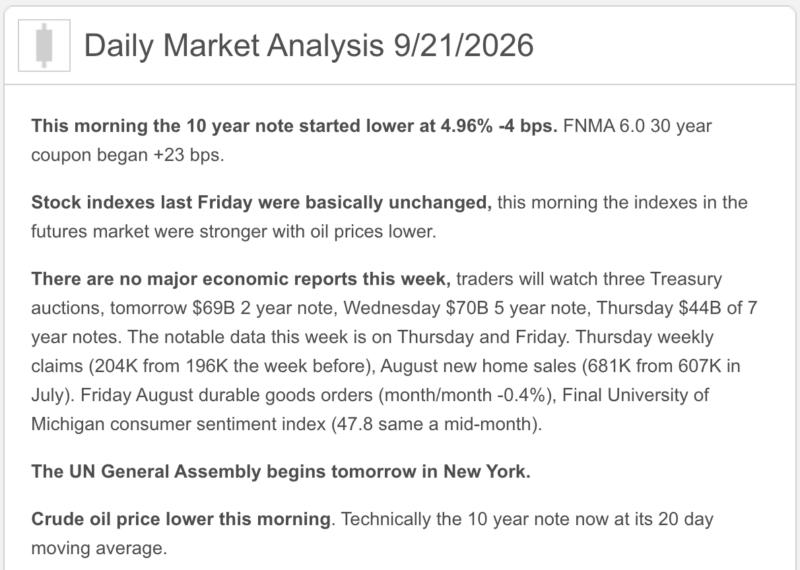
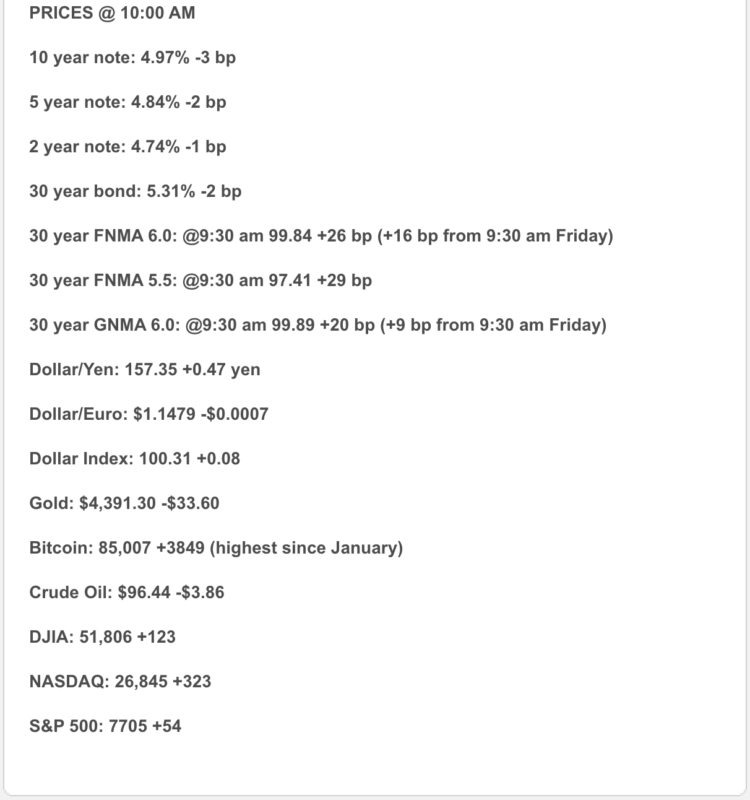
Rate sheets today will be a bit better, bringing in better pricing than last week’s worst levels, but still nothing to write home about. Oil is down on the day, helped by the usual overly optimistic reaction to President Trump’s comments that he could be open to talking with Iran President Masoud Pezeshkian at the UN General Assembly this week and by the fact that oil continues to flow from Saudi Arabia, despite the closure of its pipeline.
Reprice risk on the day is moderate, bonds will react to movement in oil prices as well as headlines about what is going on in the Middle East. It is unlikely that bonds will continue to improve much from here today, and certainly not enough to make reprices better likely. Still, cautiously floating to start is ok, and let’s see how the day plays out.
Market analysis – from a higher and better view:
Markets are beginning the week in a better mood: oil is retreating, the 10-year Treasury is below 5%, and mortgage bonds are modestly stronger.
Unfortunately, the inflation story still has more sequels than a superhero franchise.
Market analysis – Quick Snapshot
● Latest completed 30-year benchmark: 7.20%, up 0.01%
● Latest completed 15-year benchmark: 6.83%, up 0.02%
● 10-year Treasury: Approximately 4.97%, down 2–3 basis points
● Mortgage bonds: Up roughly ⅛ point intraday
● Brent crude: Approximately $101, down about 2.6%
● Stocks: Technology shares leading markets higher
Mortgage benchmarks are Friday’s completed national averages—not individual loan quotes. Treasury and MBS figures reflect Monday’s live trading. (mortgagenewsdaily.com, mortgagenewsdaily.com)
Why Is the Market Improving?
Saudi oil exports have recovered, and expectations that damaged pipeline capacity will return are helping crude prices retreat from last week’s highs.
Lower oil reduces immediate inflation pressure and is giving bonds some breathing room. (reuters.com)
However, oil remains above $100 and geopolitical risk has not disappeared.
Translation: better, not boring.
Fed Watch
Chicago Fed President Austan Goolsbee warned that inflation may now be driven by strong demand—not merely temporary oil and tariff shocks. If demand is overheating, he said the Fed may need a faster and more aggressive response.
Markets currently place roughly a 56% probability on another hike in October, with an additional increase by year-end largely priced in. (reuters.com, reuters.com)
Market analysis – Housing Check
Pending home sales increased 0.3% in August, including gains of 3.0% in the West and 2.3% in the South. However, national pending sales remain 4.7% below last year and approximately 30% below pre-pandemic levels. (mortgagenewsdaily.com)
The takeaway: demand exists, but affordability continues keeping many buyers in the waiting room.
Market analysis – Political Backdrop
President Trump signed sweeping Russia sanctions into law Friday. The measure targets Russian energy and defense industries and authorizes tariffs against major Russian trading partners—creating another potential source of commodity and trade-price volatility. (reuters.com)
Trump is also expected to meet Chinese President Xi Jinping Thursday, placing tariffs, trade and technology policy back at center stage.
What It Means
Today’s bond improvement may support slightly better mortgage pricing, but the 10-year remains caught between roughly 4.92% and 5.00%. A convincing move below that range would be more meaningful than another brief intraday rally.
Lock vs. Float
● Closing within 15 days: Lock or capture meaningful improvement.
● Closing within 15–30 days: Maintain a locking bias.
● More than 30 days: Carefully floating may be reasonable with firm pricing triggers.
Bottom line: Lower oil is helping, but Fed officials are warning that inflation may be broader than energy alone. Enjoy today’s improvement—just don’t leave it unattended near an open rate sheet.
Stay safe and make today great!