Good Friday am from your Hometown Lender. Let’s dive into today’s market analysis and try to make sense of markets this week.
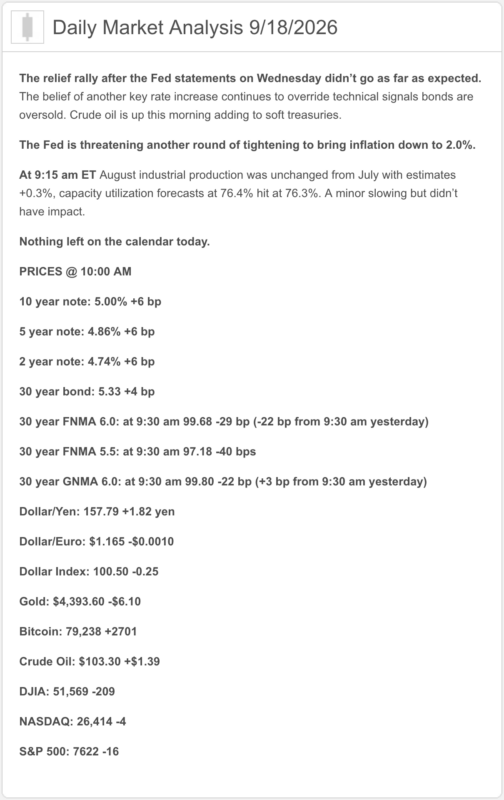
Yesterday was a good day for bonds and had everybody dancing in the streets. Surprisingly, bonds did hold their gains through the entire day, giving an inkling of hope that maybe we’d see more than just one day of recovery. However, this morning’s performance where bonds have given back about half of yesterday’s gains has dashed those hopes. Why though? Well yes, there is some profit taking when a big swing like yesterday happens but also this morning oil prices are higher and as we know, oil continues to be the lever.
Next week is not a big week in terms of economic data, but there are a few things happening that will trickle over to rates. The biggest thing, of course, will continue to be what’s going on in the Middle East..
Market Analysis – from a higher and better view:
Thursday’s bond-market celebration has run into Friday’s cleanup crew. Treasury yields are moving higher and mortgage bonds are giving back part of yesterday’s improvement—but the broader post-Fed picture remains better than it was Tuesday.
Quick Snapshot of Market Analysis
- Latest completed 30-year benchmark: 7.19%, down 0.05%
- Latest completed 15-year benchmark: 6.81%, down 0.03%
- 10-year Treasury: Approximately 5.00%, up 6 basis points
- Mortgage bonds: Down roughly ¼ point intraday
- Oil: Holding above $100
- Market tone: Defensive after Thursday’s rally
Mortgage benchmarks are Thursday’s completed national averages—not individual loan quotes. Treasury and MBS figures reflect Friday’s live trading. Mortgage News Daily
Why Are Bonds Weaker?
Some of today’s move is normal profit-taking and position-squaring after Thursday’s strong rally. Modestly higher oil and continued expectations for additional global rate hikes are also keeping inflation concerns alive.
Importantly, mortgage bonds remain stronger than they were before Wednesday’s Fed announcement despite today’s pullback. Mortgage News Daily market commentary
Market Analysis –What Hit This Morning?
U.S. manufacturing cooled. Factory output unexpectedly declined 0.3% in August after seven consecutive monthly increases. Economists had expected a 0.3% gain. The weaker reading is bond-friendly in theory, although AI-related investment continues to support longer-term activity. Reuters economic report
The global rate-hike cycle continues. The Bank of Japan raised its benchmark rate to 1.25%, its highest level in 31 years, and left the door open to additional increases. Combined with this week’s Fed hike, global central banks are clearly prioritizing inflation over cheaper borrowing. Reuters BOJ report
Fed and Political Watch
The Fed raised rates Wednesday and projected another increase this year. President Trump continues advocating substantially lower rates, placing monetary policy, affordability and Fed independence directly in the midterm-election conversation.
Separately, the House passed a bipartisan sanctions and tariff bill intended to increase economic pressure on Russia. If enacted, secondary tariffs could affect global trade and commodity pricing—another reminder that politics can quickly become an inflation report. Reuters political report
What the Market Analysis Means
Thursday’s improvement may still reach some rate sheets, but today’s weaker MBS pricing could limit how much lenders pass through. The 10-year remaining near 5% keeps mortgage rates vulnerable to oil, inflation and geopolitical headlines.
Lock vs. Float
- Closing within 15 days: Lock.
- Closing within 15–30 days: Maintain a firm locking bias.
- More than 30 days: Floating may be reasonable with defined pricing and Treasury triggers.
Bottom line: Rates improved Thursday, but Friday is reminding us that volatility has not packed its bags. Capture meaningful improvements rather than assuming the market owes us another one.
Stay safe and make today great!