Good Tuesday morning from your Hometown Lender. Here is your Tuesday market analysis!
Friday, mortgage bonds were volatile early, tanking after the stronger-than-expected jobs numbers but climbed back before settling down for the rest of the day.
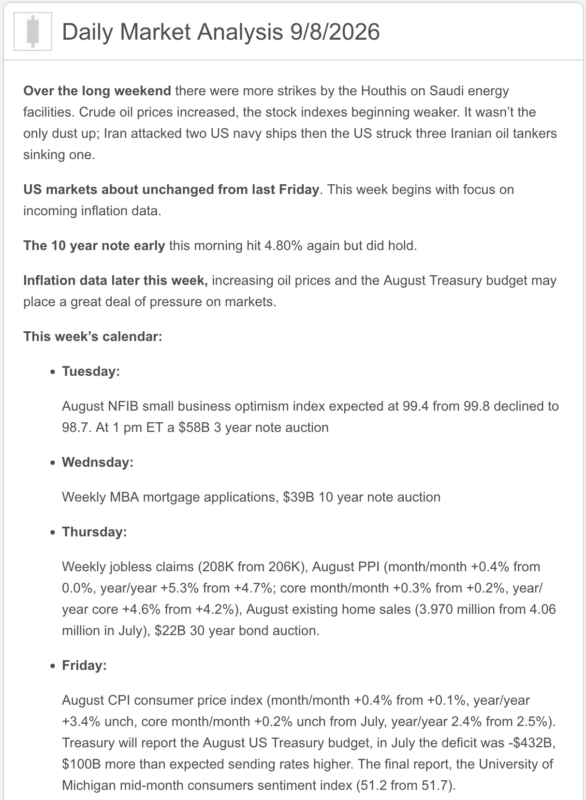
Rate sheets today likely to be similar to Friday, as bonds open the day flat despite rising oil prices. Brent crude is close to $100 a barrel again, and WTI is about $93 a barrel after Houthis attacked Saudi Arabian energy facilities. Continued attacks in the Middle East this week are likely to continue to drive up oil prices, which will contribute to higher mortgage rates.
Reprice risk today is moderate, as bonds are fighting to hold at the moment despite being pressured higher. However, there is a good chance we will see bonds sell off as the day goes on.
Market Analysis – from a higher and better view:
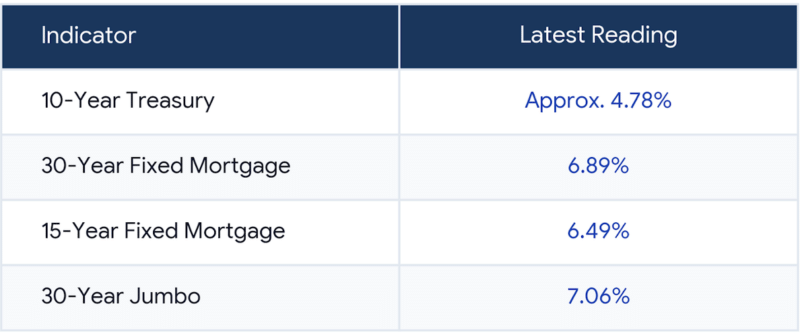
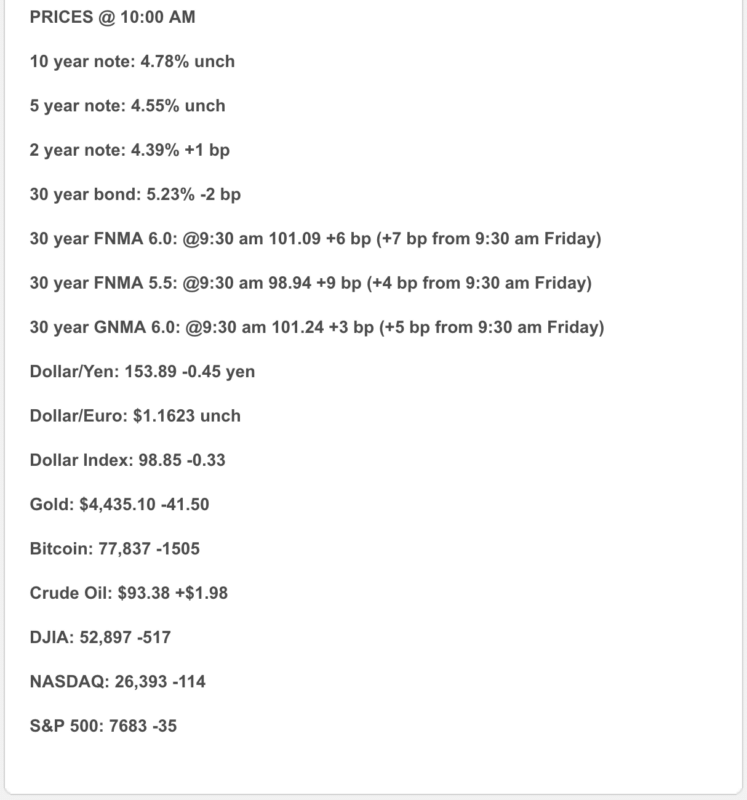
Mortgage figures are September 4 national benchmarks—the latest published averages—not personalized quotes. As of 10:59 a.m. ET today, Treasury yields were slightly lower and mortgage-backed securities were nearly unchanged. Mortgage rates · Live bond snapshot
Market Analysis – Why It’s Happening
Oil is driving the conversation. Brent crude climbed above $98 after attacks on Saudi energy facilities increased fears of broader Middle East supply disruptions. Stocks moved lower, with the Dow down approximately 1.2% and the S&P 500 and Nasdaq each off roughly 0.5%. Reuters
Oil near $100 presents two problems: higher consumer costs and renewed inflation pressure. Both can encourage the Federal Reserve to keep rates elevated—even if economic growth begins slowing.
Small-business confidence softened. The NFIB Optimism Index declined from 99.8 to 98.7 in August, although it remains slightly above its long-term average. Inflation was identified as the most important problem by 16% of owners, while sales expectations and hiring plans weakened. NFIB
That combination—less confidence but continuing cost pressure—is not the economic cocktail anyone ordered.
Political & Global Backdrop
The United States announced 36 additional Iran-related sanctions, primarily targeting Iranian airlines, overseas intermediaries and aviation-procurement networks. The measures expand Washington’s economic-pressure campaign as regional fighting enters its seventh month. Reuters
For mortgage markets, the politics matter because sanctions, military escalation and disrupted shipping can keep energy prices—and therefore inflation expectations—elevated.
Market Analysis – What It Means
Today’s modest Treasury improvement is encouraging, but oil and inflation risk limit the celebration. The market’s next major tests are:
- Producer Price Index: Thursday at 5:30 a.m. Pacific
- Consumer Price Index: Friday at 5:30 a.m. Pacific
Both reports could produce immediate mortgage-pricing volatility. BLS calendar
Lock vs. Float
- Closing within 15 days: Favor locking.
- Closing in 15–30 days: Maintain a modest locking bias.
- Beyond 30 days: Floating may be reasonable with sufficient budget flexibility and a firm lock trigger.
Bottom line on today’s market analysis: A quiet bond market doesn’t necessarily mean a quiet week. With inflation data approaching and oil near $100, payment certainty deserves a seat at the table.
Stay safe and make today great!