Good Tuesday morning from your Hometown Lender. Here is today’s fresh market analysis!
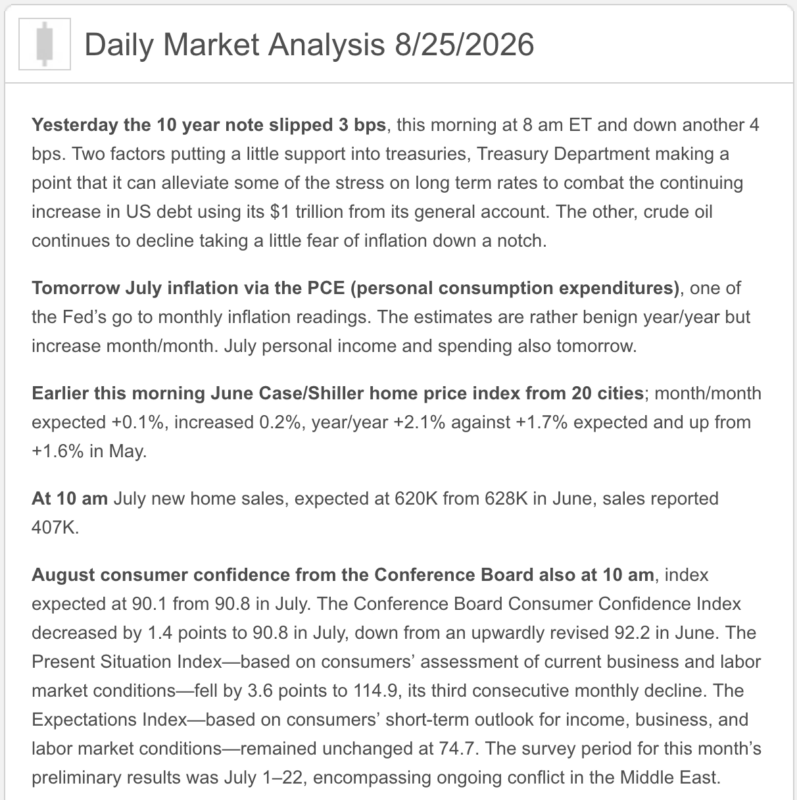
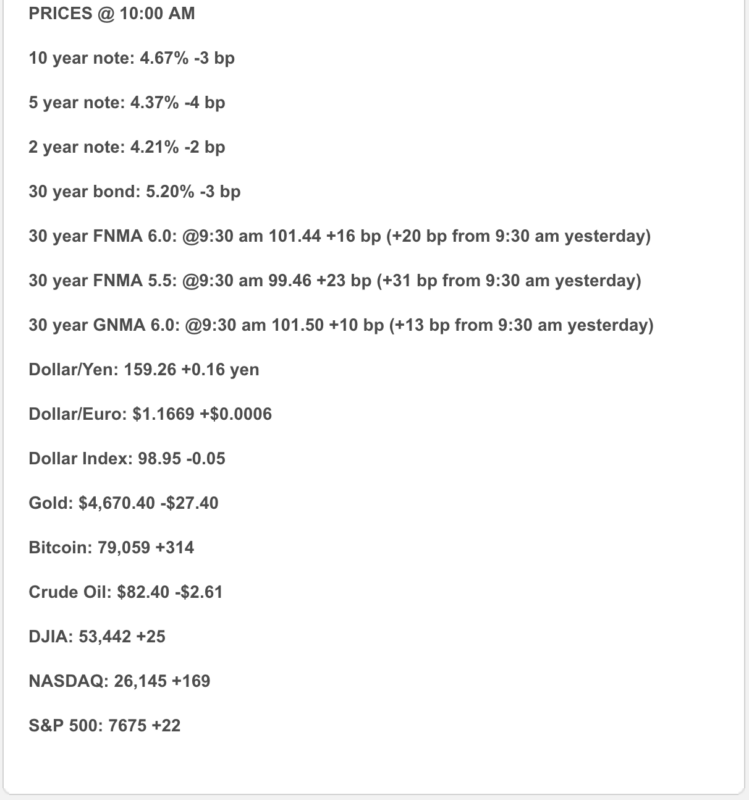
Rates are a bit better today than yesterday. Bonds helped today from falling oil prices, with Brent crude back below $90 a barrel and some optimism that it could move lower. Nothing of note on the economic calendar today, but the PCE inflation data on the calendar for tomorrow. The outlook is a bit better today than it has been, the 10yr yield has fallen back below 4.70 and mortgage bonds are improving on the day. That said though, we still aren’t likely to see rates improve all that much from here.
Market Analysis – From a higher and better view:
Market Analysis –Quick Snapshot
- 10-year Treasury: approximately 4.66%, improving about 5–6 basis points
- 30-year conventional: approximately 6.77%
- 15-year conventional: approximately 6.08%
- FHA: approximately 6.45%
- Jumbo: approximately 6.71%
- 7/6 SOFR ARM: approximately 5.94%
- Stocks: Modestly higher, led by technology
- Oil: Lower, providing some welcome inflation relief
Rates vary by borrower, property, loan structure and points. Market data
Market Analysis –Why It’s Happening
Treasury yields are retreating as oil prices fall and markets respond positively to the Treasury Department’s plan to expand purchases of longer-term government bonds. Lower oil is especially helpful because energy costs can quickly spread through transportation, manufacturing and consumer prices.
The catch: inflation remains stubborn. Boston Fed President Susan Collins warned that rates may need to rise unless inflation resumes a convincing decline. Translation: the Fed has not yet put the inflation fire extinguisher back in the cabinet.
Market Analysis –Today’s Economic News
July new-home sales fell 10.5% to an annualized 607,000, missing expectations. Sales were also 6.3% below last year, while the median price declined to $393,800. Higher rates and affordability pressures continue to restrain demand. Census housing data
Consumer confidence also slipped for a second consecutive month as households expressed greater concern about jobs, food costs and gasoline prices.
Political & Global Backdrop
Washington expanded sanctions against Iran, but the measures were less aggressive than markets feared. Oil prices declined as traders concluded that the immediate threat to global supply had not materially increased.
Meanwhile, trade tensions—including tariffs and strained negotiations with Canada—remain a longer-term inflation risk. Tariffs may raise revenue, but they can also raise prices. The economy rarely offers a free lunch, and lately even lunch is more expensive.
What Markets Are Watching
Tomorrow brings a major double feature for market analysis:
- The revised estimate of second-quarter GDP
- July PCE inflation, the Fed’s preferred inflation gauge
A cooler core PCE reading could help bonds and mortgage pricing. A hotter result could quickly reverse today’s improvement. BEA release calendar
What It Means for Buyers and Sellers
Buyers remain payment-sensitive, but softer sales and increased builder competition may create negotiating opportunities. Sellers must price accurately from day one; transpiration pricing is currently receiving very realistic feedback from the market.
A temporary improvement in yields is encouraging, but affordability—not a lack of desire to buy—remains housing’s primary constraint.
Market Analysis –Lock vs. Float
- Closing within 15 days: Favor locking.
- Closing within 15–30 days: Maintain a modest locking bias.
- More than 30 days out: Carefully floating may be reasonable, but tomorrow’s inflation report creates meaningful volatility risk.
Today’s bond improvement is helpful, but with major data arriving tomorrow, this is not the moment to confuse a good morning with a permanent trend.
Stay safe and make today great!