Good Friday morning from your Hometown Lender. Let’s dive into your FridYAY market analysis!
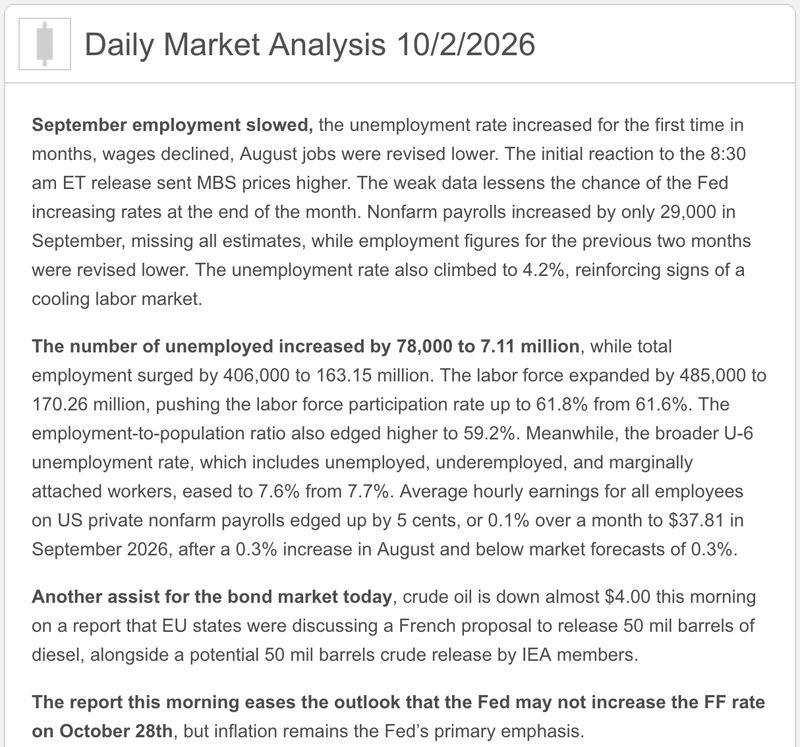
Today is jobs report day. Arguably the biggest economic report of the month and once the Fed is certainly watching before their October meeting. At the headline number, it was dismal showing just 29k jobs were creates vs 90k forecast.
Mortgage bonds jumped on the news and were up more than 3/8ths and the 10yr was down almost 8 bps at the lowest levels. That’s the good news. But even early on it seemed like the rally should be bigger for such a hotly anticipated report.
Why wasn’t it?
Yes, the Fed has said to focus more on the unemployment rate than other data but in today’s case, it only rose to 4.175% (reported as the rounded up 4.2%) from 4.141% last month (rounded down to 4.1%). Moreover, it did so despite the participation rate rising 0.2%. In other words, had it not been for that 0.2% uptick in participation, Unemployment would have come in at 3.951%.
Bottom line: this report wasn’t really weaker than expected apart from wage growth. The market took a bit but figured it out and as I type, has reversed and is down on the day. I think we will close better but if you are looking for the reason why we are not much better, this is it.
Market Analysis – From a higher and better overall view:
The jobs report tapped the brakes. Bond traders eased off the horn.
💼 Market Analysis – What Hit This Morning
September payrolls increased 29,000, well below the 90,000 economists expected. Unemployment ticked up to 4.2% from 4.1%.
The revisions matter, too: July and August combined were reduced by 60,000 jobs. Average hourly earnings rose 0.1% monthly and 3.0% annually.
My read: hiring looks softer, giving the Fed more reason to be patient. One report can be noisy, but weaker revisions deserve attention. For households, income stability remains just as important as the interest rate.
📊 Market Analysis – Where Mortgage Rates Stand
Latest completed Mortgage News Daily benchmarks, October 1:
| Loan type | Benchmark rate |
| 30-year fixed | 7.54% |
| 15-year fixed | 7.18% |
| 30-year jumbo | 7.66% |
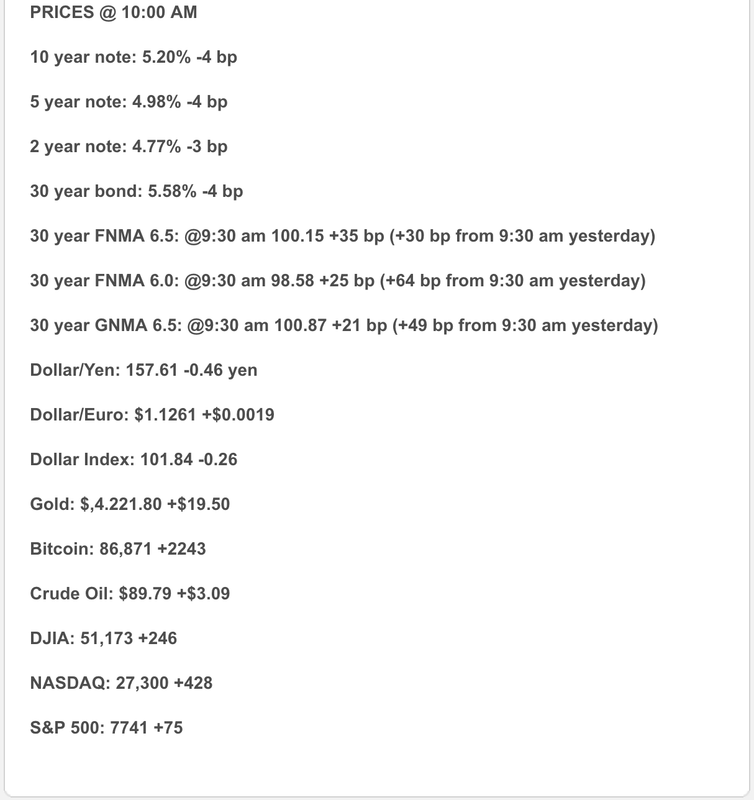
Friday morning’s snapshot: 10-year Treasury near 5.20%; mortgage bonds stronger. That gives lender pricing a more supportive backdrop. These benchmarks are not personalized loan quotes; today’s terms depend on your scenario and lender.
🏦 Markets & Fed Watch
At the opening, the S&P 500 rose 0.9% and the Nasdaq gained 1.2%. Traders reduced expectations for another Fed rate increase in October.
Market analysis: A pause would give the economy time to digest higher borrowing costs. It would not automatically mean rate cuts or a matching move in mortgage rates.
The next major inflation checkpoint is CPI on October 14, followed by PPI on October 15. Today’s report helps the case for patience; inflation still gets a vote.
🌎 Politics & Energy
President Trump said Europe agreed to release diesel reserves. Reuters reported that agreement on the proposed volumes among G7 countries remained unclear.
Why borrowers should care: fuel costs flow into transportation, construction and household budgets. Additional supply could ease pressure, but an announcement alone does not resolve the underlying disruptions.
🏡 Your Weekend Housing Playbook
- Buyers: Refresh your quote before touring. Compare the full payment, cash to close and reserves after closing.
- Agents: Revisit financing and seller-credit options before negotiating weekend offers.
- Homeowners: Recheck refinance economics using actual costs and your expected time in the loan.
🔒 Lock vs. Float
Market Analysis:
- Closing soon? If improved pricing meets your budget, consider protecting it.
- Already locked? Ask whether your lender offers a float-down and what conditions apply.
- Floating? Set a deadline and a limit for how much worse pricing you can absorb.
A favorable market move is useful. A comfortable payment is the goal.
Stay safe and make today great!