Good Thursday am from your Hometown Lender. Let’s dive into good news in today’s market analysis, shall we?
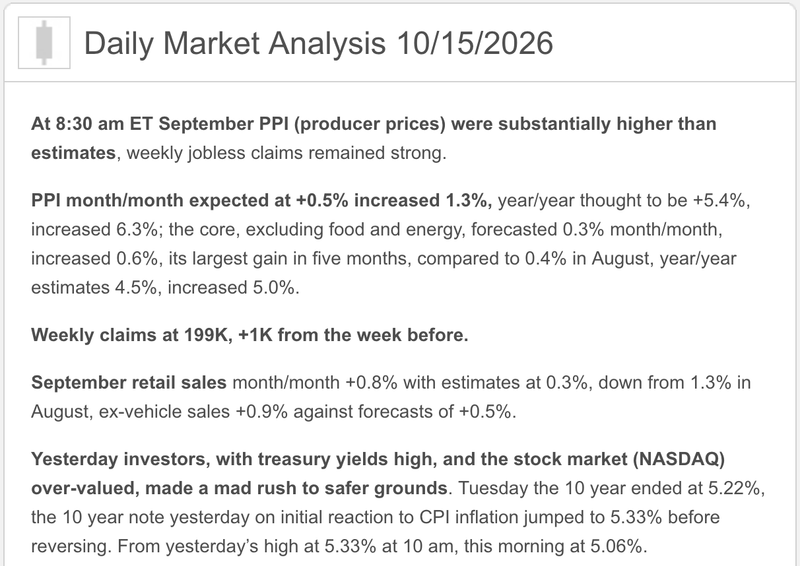
Core PPI was up 0.7 vs 0.3 forecast this morning. That’s something that would normally send yields much higher. But everything is different this morning. Bonds rallied sharply in the overnight session and added a bit more to the gains after the 8:30am data. This is on top of yesterday’s stunning comeback after getting rocked by higher CPI. To a small extent, the “control group” Retail Sales number may have helped, but the 8:30am gains have more to do with investors waiting to see PPI and finding it would add less than 0.1% to PCE in 2 weeks. This allows the market to maintain its focus on the biggest motivation of the past 2 days: concerns over an AI debt bubble (and big losses in several AI stocks) leading investors to reallocate bond exposure back into Treasuries and portfolio managers to pare equities holdings in favor of bonds. All of the above conveniently coincided with bond yields hitting decades-long highs last week and still being high enough to look like a good buying opportunity today.
Market Analysis – From a higher and better view:
Preview: Producer inflation surged, but a tech-led flight to safety gave bonds—and mortgage pricing—a friendlier morning.
Hot PPI. Falling yields. No typo—Thursday brought a genuine market plot twist.
📊 Mortgage & Bond Market Analysis Snapshot
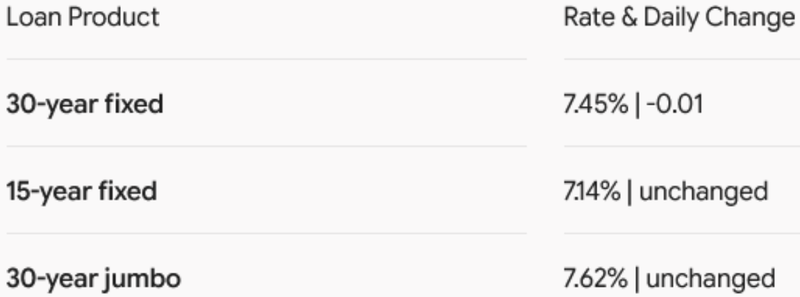
Latest completed Mortgage News Daily benchmarks, Wednesday, October 14:
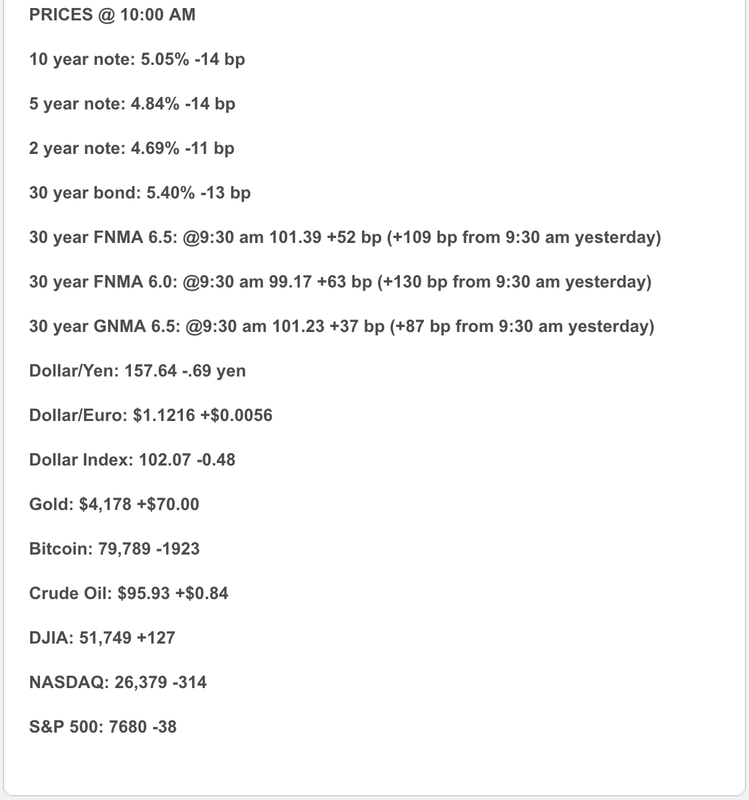
This morning, the 10-year Treasury yield was near 5.06%, down about 12 basis points, while UMBS 6.0 mortgage bonds were roughly 0.55 higher. Mortgage News Daily described MBS as significantly stronger—an intraday setup that should support lower lender pricing today.
That is encouraging, not a blank check. The MND rate index is yesterday’s completed national benchmark; actual pricing changes intraday and depends on credit, equity, occupancy, loan type and points.
🔥 Market Analysis – Inflation: PPI Was Hot—Very Hot
September producer prices jumped 1.3% for the month—the largest increase since March 2022—and 6.3% year over year. Economists expected a 0.5% monthly gain. Goods prices rose 2.6%, services rose 0.8%, and gasoline surged 20.3%. The less-food-energy-and-trade measure rose 0.5% monthly and 5.0% annually.
Translation: energy was the headline amplifier, but the heat was not confined to energy. Hotels, airfares, freight and trade margins also moved higher. Inflation did not merely knock; it used the garage door.
🛒 Consumer & Labor Check
Retail sales rose 0.8% in September versus a 0.3% forecast, but the details were less muscular: gas-station receipts jumped 6.4%, while the GDP-linked control group rose only 0.1%, below the 0.3% expectation.
Initial jobless claims edged up to 199,000, marking a fifth straight week below 200,000. Continuing claims slipped to 1.710 million. That is still a low-hire, low-fire labor market: layoffs remain limited, while hiring is hardly throwing a parade.
🤹 Why Did Bonds Rally Anyway?
Normally, market analysis this hot would push yields higher. Today, concerns about debt-funded AI investment and a deepening technology selloff sent investors toward the relative safety of Treasuries. Mortgage News Daily also noted that the PPI components feeding the Fed’s preferred PCE gauge may add less than one-tenth to that report.
At 9:50 a.m. ET, the Nasdaq was down 1.06%, the S&P 500 was down 0.42%, and the Dow was up 0.32%. The 10-year yield touched a three-week low near 5.07%.
In short: stocks supplied the fear; bonds collected the flight-to-safety money.
🏦 Fed Watch
Markets were pricing roughly a 25%–30% chance of an October rate hike and a 70%–75% chance of a hold for the Fed’s October 27–28 meeting.
The Fed raised its policy range to 3.75%–4.00% in September. Today’s bond rally helps mortgage markets, but hot inflation keeps the Fed’s options uncomfortably open.
🏛️ Market Analysis – Politics & the Affordability Vote
With the November 3 midterms less than three weeks away, affordability is the closing argument.
A new AP-NORC poll found about 8 in 10 registered voters disapprove of President Trump’s handling of the cost of living, while roughly 3 in 4 disapprove of his handling of the economy.
The practical market point is nonpartisan: inflation, gas, housing and interest rates are now campaign issues as much as economic data.
🎯 Put Thursday’s News to Work
- Buyers: Ask for a fresh payment today; a favorable intraday reprice may matter more than yesterday’s headline rate.
- Agents: Compare a seller credit, temporary buydown and price reduction on the same page.
- Homeowners: Treat refinance or equity decisions as break-even math—not a reaction to one volatile morning.
🔒 Lock vs. Float
- Closing in 0–15 days: Lean toward protecting a payment that works, especially if today’s rally reaches your lender’s rate sheet.
- Closing in 16–30 days: A cautious float can be reasonable only with a written trigger and room for reversal.
- More than 30 days out: Focus on structure, concessions and multiple scenarios; today’s rally is useful information, not a forecast.
The market analysis takeaway: this is an opportunity window—not permission to daydream. The market can hand back a rally faster than it handed it out.
Stay safe and make today great!