Good morning on this best day of the week Wednesday from your Hometown Lender. Here is your hump day market analysis!
Yesterday bonds were choppy early, but settled down and were unchanged through the rest of the day as markets waited for today’s CPI inflation data.
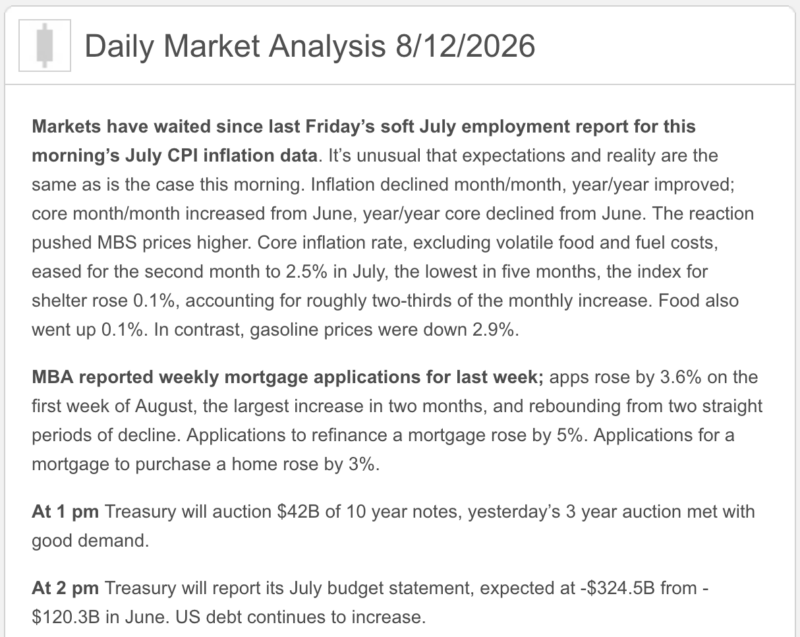
The Consumer Price Index (CPI) came in right at expectations this morning, across the board. The headline inflation rate cooled to 3.4% in July, slightly lower than the 3.5% in June. Core prices (minus food and energy) rose by 2.5% over the past year, down from 2.6% in June. The numbers were enough to ease markets concerns that the Fed would hike rates in September, pushing bets on a rate hike.
With that, rates are a bit better than yesterday, but not by much. Still, until we see a resolution in the Middle East and oil prices back down (Brent down in the low $70’s and WTI in the low $60’s), we aren’t likely to see rates move lower.
Market Analysis – From a higher view:
Market Analysis – Quick Snapshot
- Inflation — Better News: July CPI rose just 0.1% for the month and 3.4% year over year, down from 3.5% in June. Core CPI increased 0.2% monthly and eased to 2.5% annually. Gasoline prices fell 2.9%, while shelter accounted for roughly two-thirds of the monthly increase. Inflation is cooling—not cured—but today’s report definitely earned a gold star.
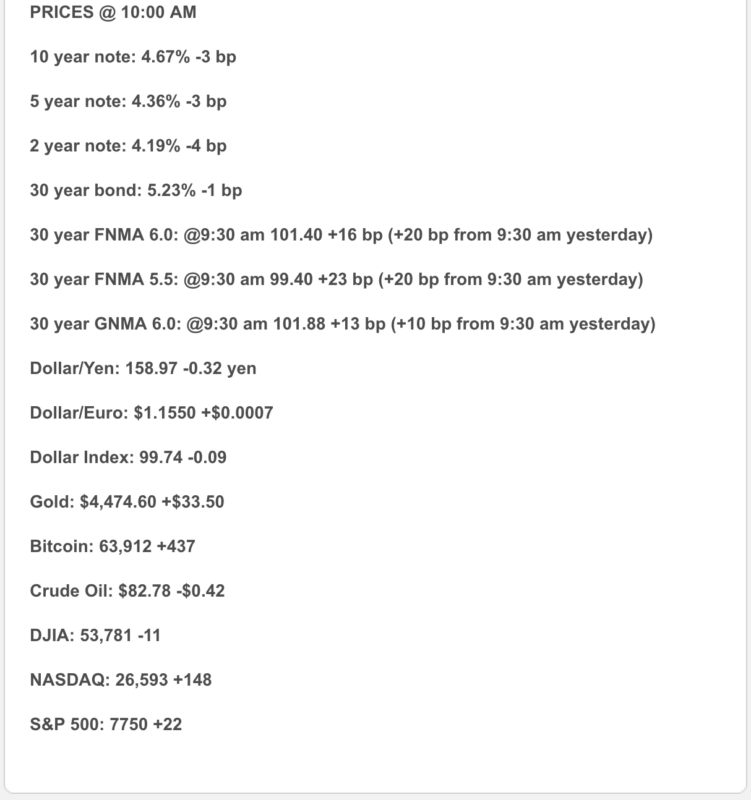
- 10-Year Treasury: The 10-year is near 4.66%–4.67%, down modestly following CPI. The reaction has been surprisingly restrained, suggesting investors liked the report but want more evidence before declaring an inflation victory.
- Mortgage Rates: Today’s national averages have improved to approximately 6.72% for a 30-year fixed and 6.07% for a 15-year fixed. Freddie Mac’s latest weekly survey remains at 6.69% for the 30-year.
- Fed Watch: Markets now put the probability of a September Fed hike around 39%–40%, down from roughly 48% before CPI. Combined with July’s unexpected job losses, today’s inflation report strengthens the argument for the Fed to remain on hold at 3.50%–3.75%.
- Oil & Geopolitics: Brent crude is near $88.70, with WTI around $82.80. U.S.–Iran negotiations remain deadlocked, and Iran says the Strait of Hormuz will stay closed unless its conditions are met. Oil remains the biggest wildcard because today’s CPI does not fully capture the latest energy-price increase.
- Housing: July existing-home sales fell 1.7% to a 4.06 million annualized pace. The median price increased 2% to $434,100, while first-time buyers accounted for just 29% of purchases. Higher rates haven’t eliminated demand—they’ve increasingly divided the market by affordability.
- Politics: Inflation remains politically important heading toward November’s midterms, while President Trump’s renewed effort to remove Fed Governor Lisa Cook has put Federal Reserve independence back into the market conversation. Political pressure for lower rates may sound mortgage-friendly, but anything that increases long-term inflation concerns can actually push Treasury and mortgage rates higher.
Why It’s Happening
Today’s market analysis equation is improving:
Cooling inflation + weaker employment = less pressure on the Fed to hike.
But:
Elevated oil + tariffs + geopolitical uncertainty = inflation risk is not gone.
In plain English: Inflation finally brought us some flowers. The bond market is wisely waiting before changing its relationship status.
Market Analysis – What It Means
Today’s CPI is genuinely constructive for mortgage rates.
We now have softer employment and moderating consumer inflation, two ingredients’ bonds have been waiting for.
The next test comes tomorrow morning with July PPI, followed by retail sales on Friday. PPI matters because several of its components ultimately feed into the Fed’s preferred PCE inflation gauge.
Housing & Mortgage Strategy
This remains a structure-the-payment market.
Seller credits • Temporary/permanent buydowns • Builder incentives • Strategic ARM options • Debt consolidation • Future refinance planning
With rates improving modestly today, buyers who were already qualified and engaged are in the best position to benefit.
The lesson: Don’t wait to get ready when rates fall. Get ready so you can act when they do.
Lock vs. Float
Closing within 15 days: Lock bias. Today’s improvement is worth protecting.
15–30 days: Balanced / cautious float. CPI helped, but tomorrow’s PPI creates another event risk.
30+ days: A managed float has become more defensible if inflation continues cooling.
Today’s market analysis:
Take advantage of improvement without getting greedy. A good rate today is real; a better rate tomorrow is still a forecast.
Stay safe and make today great!